
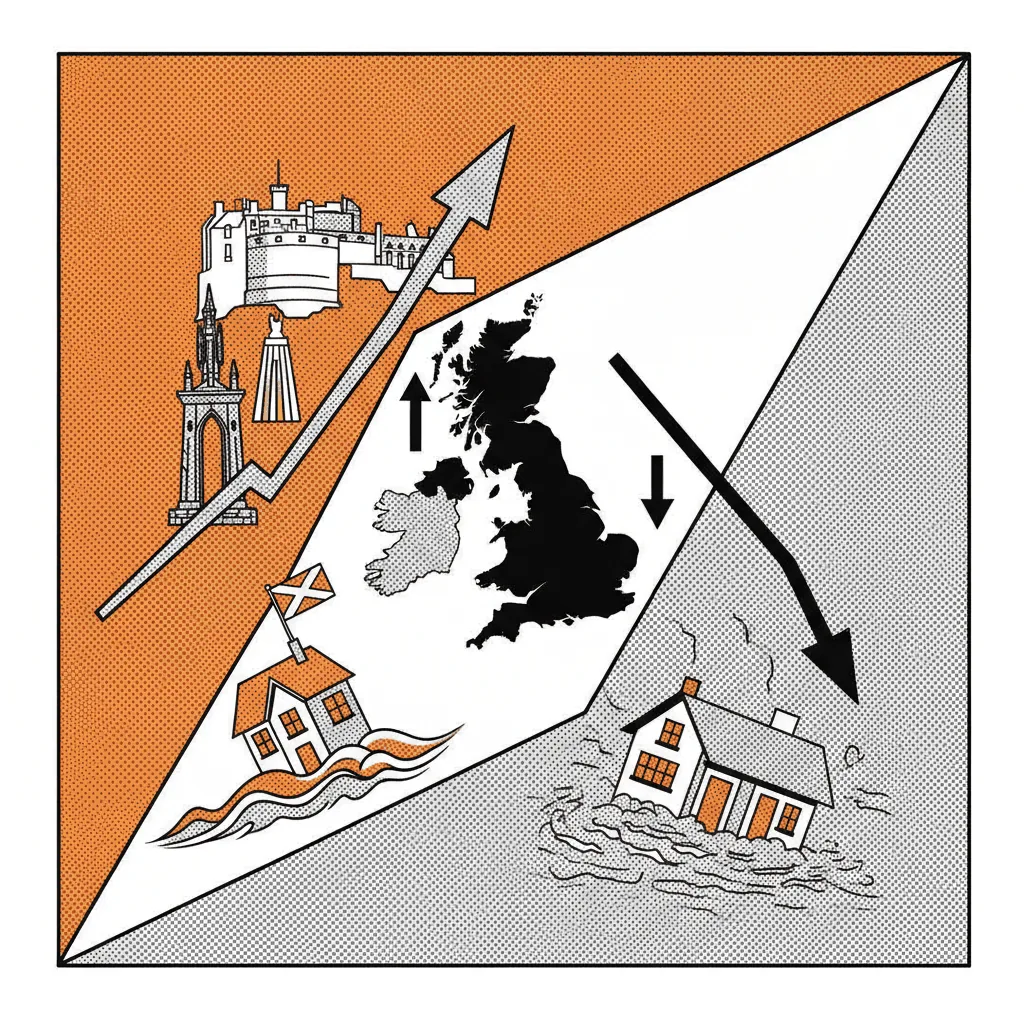
The UK housing market has posted its first annual price decline in nearly three years, according to the latest data from Lloyds Bank, one of Britain's largest mortgage lenders. Average UK house prices have dipped on a year-on-year basis for the first time since 2023, a meaningful reversal after a sustained period of post-pandemic growth. Scotland, however, is moving in the opposite direction, with average Scottish house prices continuing their upward trajectory and bucking the national trend.
This is not a minor regional blip. A diverging property market between Scotland and the rest of the UK has structural implications. According to the Office for National Statistics, Scottish house price growth had already been outpacing the UK average across much of the past two years, driven by relative affordability, population movement into cities like Edinburgh and Glasgow, and a supply base that simply hasn't kept pace with demand. When the UK tide goes out and Scotland keeps rising, that gap becomes commercially significant.
For SME owners, the property they operate from, own, or lease is often the largest single asset on the balance sheet. A strengthening Scottish market means collateral values are holding or improving at a time when English counterparts may be watching their asset base soften. That has direct implications for borrowing capacity, refinancing terms, and any plans to use property equity to fund growth. The Bank of Scotland's own regional data has consistently shown Edinburgh and the central belt outperforming wider UK averages, and Lloyds' latest figures reinforce that picture.
There is also a rental market dimension here. With property values rising and demand sustained, commercial and residential landlords operating in Scotland face a different calculus than their counterparts in the south. The Scottish Government's approach to rental regulation, including rent control measures under the Cost of Living (Tenant Protection) (Scotland) Act, remains a live policy factor. But on the raw asset side, Scottish property is holding its value in a market where that is no longer guaranteed elsewhere in the UK.
The wider context matters too. The Bank of England's interest rate cycle, while easing slowly, continues to constrain buyer appetite across the UK. According to UK Finance, mortgage approvals have remained subdued through early 2025. That restraint is clearly weighing on English and Welsh markets more heavily than on Scotland, suggesting that Scottish demand is being supported by factors beyond cheap credit: inward migration, public sector employment concentration, and the relative cost-of-entry compared to London and the South East. Scotland, in short, is benefiting from being genuinely affordable by comparison, and that advantage compounds when the expensive markets correct first.
None of this means Scottish property is immune to a broader correction if UK economic conditions deteriorate sharply. But right now, the data is clear: Scottish SMEs sitting on property assets are in a materially stronger position than the UK headline suggests, and that is worth understanding precisely before making any decisions about refinancing, expansion, or disposal.