
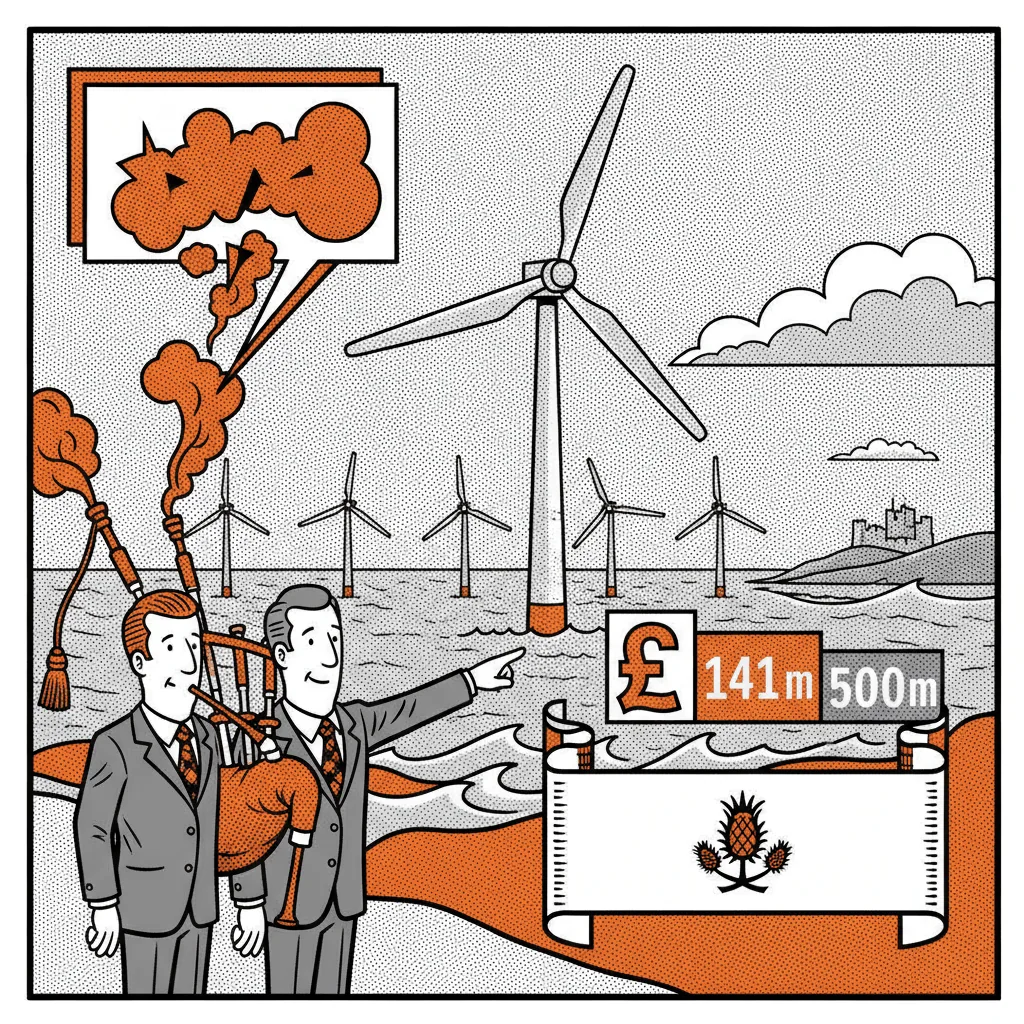
The Offshore Wind Investment Programme launched in 2023 with a simple, ambitious pitch: £500 million of public money over five years to build a Scottish supply chain capable of competing for the enormous wave of offshore wind contracts coming down the line. As of now, only £141 million of that has been committed. That's 28p in every promised pound, and the clock is ticking.
The programme exists because Scotland has a genuine structural problem. The country has world-class wind resources, a growing pipeline of offshore projects, and a government that has staked significant political capital on becoming a clean energy powerhouse. What it has lacked is a mature domestic supply chain to capture the economic value. Too many contracts, from turbine components to installation vessels to subsea cabling, have historically flowed to European manufacturers rather than Scottish yards and fabricators. OWIP was designed to change that arithmetic.
According to Scottish Business News, the programme faces multiple risks beyond the slow pace of commitment, though the Scottish Government has not yet published a detailed breakdown of where the delays are concentrated. What is clear is that five-year programmes with large capital ambitions tend to front-load expectations and back-load delivery, which is exactly what appears to be happening here. The Scottish Government's own figures on renewable energy investment, cited in its Energy Strategy and Just Transition Plan, project that offshore wind could support up to 17,000 Scottish jobs by 2030, but that scale of employment depends on supply chain development moving faster than current OWIP progress suggests.
Crown Estate Scotland, which manages seabed leasing for offshore developments, has reported significant interest from developers in Scottish waters, with projects including Scotwind licences representing potential installed capacity of around 25 gigawatts. The prize is real. But industry bodies including Scottish Renewables have consistently flagged that without sustained, timely investment in ports, fabrication facilities, and workforce training, Scottish firms risk watching that work go elsewhere, to Danish, German, or Dutch competitors with deeper infrastructure and longer track records. A slow-moving fund is not a neutral outcome; it is a competitive disadvantage measured in contracts lost.
For Scottish SMEs already working in or adjacent to the energy sector, the honest read is this: the opportunity remains significant, but the timeline for public money reaching the ground is longer than the programme's launch suggested. Businesses building their growth plans around OWIP-backed contracts in 2024 or early 2025 may need to stress-test those assumptions. The Scottish Government's commitment to offshore wind is not in question; the execution pace is. Watching for the next formal OWIP progress update, and tracking which specific supply chain segments are drawing investment first, will tell you more than any press release about where the real contracts are forming.