
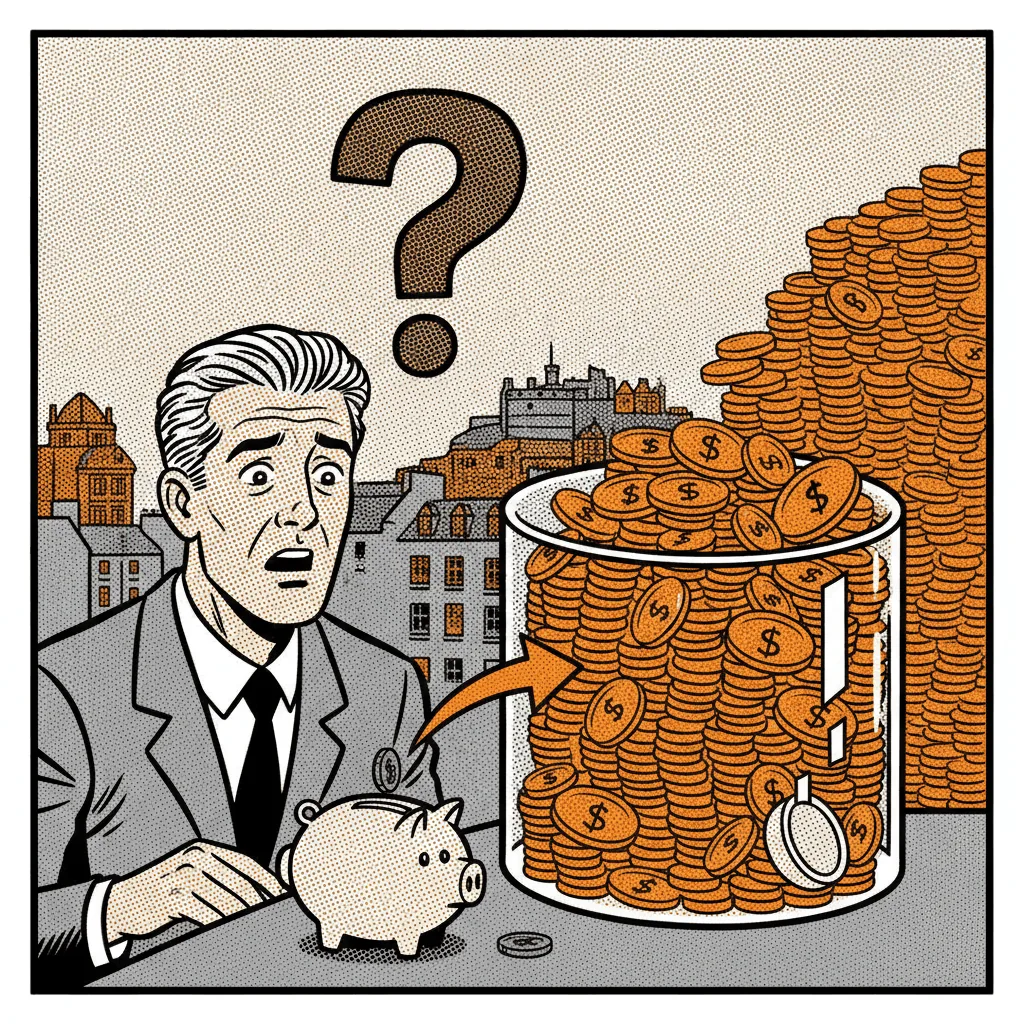
Ninety-six percent. That is the share of fully self-employed workers in the UK who are not saving into a pension, according to research cited by Startups.co.uk. For Scotland's growing freelance and solopreneur community, estimated at over 330,000 self-employed workers according to the Scottish Government's labour market statistics, that figure is not a curiosity. It is a slow-motion crisis playing out across every coworking space, spare bedroom, and converted garage in the country.
The structural reason is well understood. Employees get auto-enrolment: their workplace pension ticks along in the background, with employer contributions topping it up, and most people never have to think about it. The self-employed get nothing of the sort. No nudge, no matching contribution, no default. Just a blank where the safety net should be. The Pensions Policy Institute has repeatedly flagged this gap as one of the most serious long-term financial risks facing the UK workforce, and the self-employed share of that workforce has grown significantly over the past decade.
The practical options are better than most freelancers realise. A Self-Invested Personal Pension, commonly called a SIPP, lets you choose your own investments and contributes with full tax relief, meaning a basic-rate taxpayer effectively gets £125 deposited for every £100 they put in. For higher-rate Scottish taxpayers, that relief climbs further. Platforms like Vanguard, PensionBee, and Nest (which opened to the self-employed in 2016) have stripped out much of the complexity. You do not need a financial adviser to get started, though speaking to one before making larger contributions is always worth the hour.
The other angle freelancers miss is timing. The earlier you open a pension, even with a modest monthly amount, the harder compound growth works on your behalf. According to the Money and Pensions Service, someone starting at 30 contributing £200 a month could accumulate significantly more than someone who waits until 40 and doubles their contributions. Delay is the most expensive financial decision most solopreneurs never notice they are making. Scotland's Business Gateway offers free financial planning signposting for sole traders and small businesses, a resource that too few people use.
There is also a tax planning dimension worth flagging. If your business has a good year, making a larger one-off pension contribution before your tax return deadline can reduce your income tax bill while simultaneously building your retirement pot. For limited company directors operating through their own company, employer contributions made by the company are treated as a business expense, meaning they are not subject to National Insurance either. That is a meaningful efficiency that many Scottish freelancers who have incorporated simply do not know about. A conversation with an accountant who understands self-employment pays for itself quickly here.